
Financial fitness 101: What you need to know before taking out a loan
Johannesburg - Many people start off the year promising that they will get gym-fit. But, getting financially fit is every bit as important.
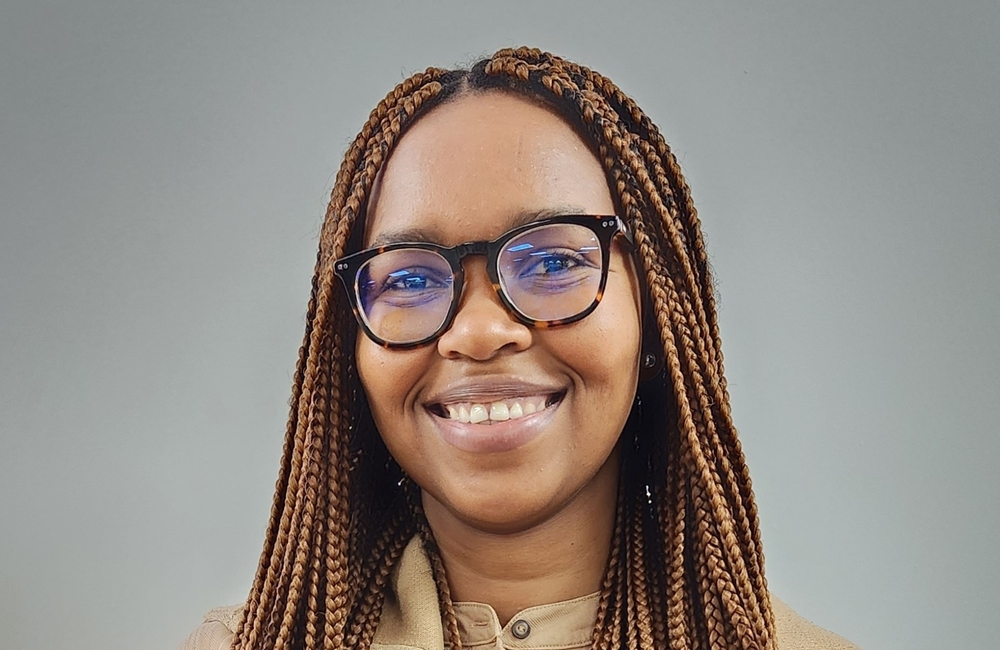
This is according to Nasia Seyuba, Head of People at FinChoice, a registered credit provider. “Financial fitness is partly about budgeting and saving, and partly about understanding and managing debt. This is especially important at this time of year, when you may be considering borrowing money for school fees and other yearly expenses.”
When it comes to personal loans, revolving credit, and other types of debt, financial fitness starts with understanding the terms and conditions. If the lender does not provide terms and conditions before you commit, it could mean that they are not a registered credit provider and that their offering may not be in line with legal requirements. This, in turn, could leave you open to interest rates and payment terms that are difficult to meet.
It is easy to check whether credit providers are registered: they must include their registration number, which starts with ‘NCR’, on all their communication, and the National Credit Regulator can confirm whether it is valid.
Understanding the terms and conditions will also help you to understand the real cost of a loan. A proper breakdown should include:
- The interest rate being charged, and whether it is fixed for the loan term or likely to change.
- Your total amount of your monthly payment.
- Whether the lender can decide to increase the interest rate at any point in time.
- Any penalty fees that will be charged if you miss a payment.
- Any additional initiation (starting) and admin fees.
Then it is vital to understand how the lender will communicate with you. Credit agreements can be changed from time to time, but the lender must tell you about any changes before they implement them. Keep an eye out for letters, emails and messages, and ensure that the lender always has your most up to date contact details. Lenders only have to show that they have sent a letter. They do not have to prove that you have opened or read it; this is your responsibility.
Another thing to check is how easy it is for you to contact the lender. Do they respond quickly and meaningfully to WhatsApp messages and emails? Do they answer if you phone their call centre? Is their website or app easy to use? If not, think twice.
“Being financially fit means feeling confident and secure about your financial situation. Doing some research and reading the terms and conditions before committing to a loan can mean the difference between flexing real financial muscle and being trapped under a weight that is too heavy to lift,” says Seyuba.



 Banking Biz proudly displays the "FAIR" stamp of the Press Council of South Africa, indicating our commitment to adhere to the Code of Ethics for Print and online media which prescribes that our reportage is truthful, accurate and fair. Should you wish to lodge a complaint about our news coverage, please lodge a complaint on the Press Council's website, www.presscouncil.org.za or email the complaint to enquiries@ombudsman.org.za. Contact the Press Council on 011 4843612.
Leave a Reply